What This Video Covers
This is the third episode of the neighborhood buyer series. Each one takes a single neighborhood, pulls the real MLS data, and puts the four numbers a buyer actually needs on the screen: what is for sale, what it costs a month, what you have to earn, and what credit score gets you in.
The number that makes this neighborhood different
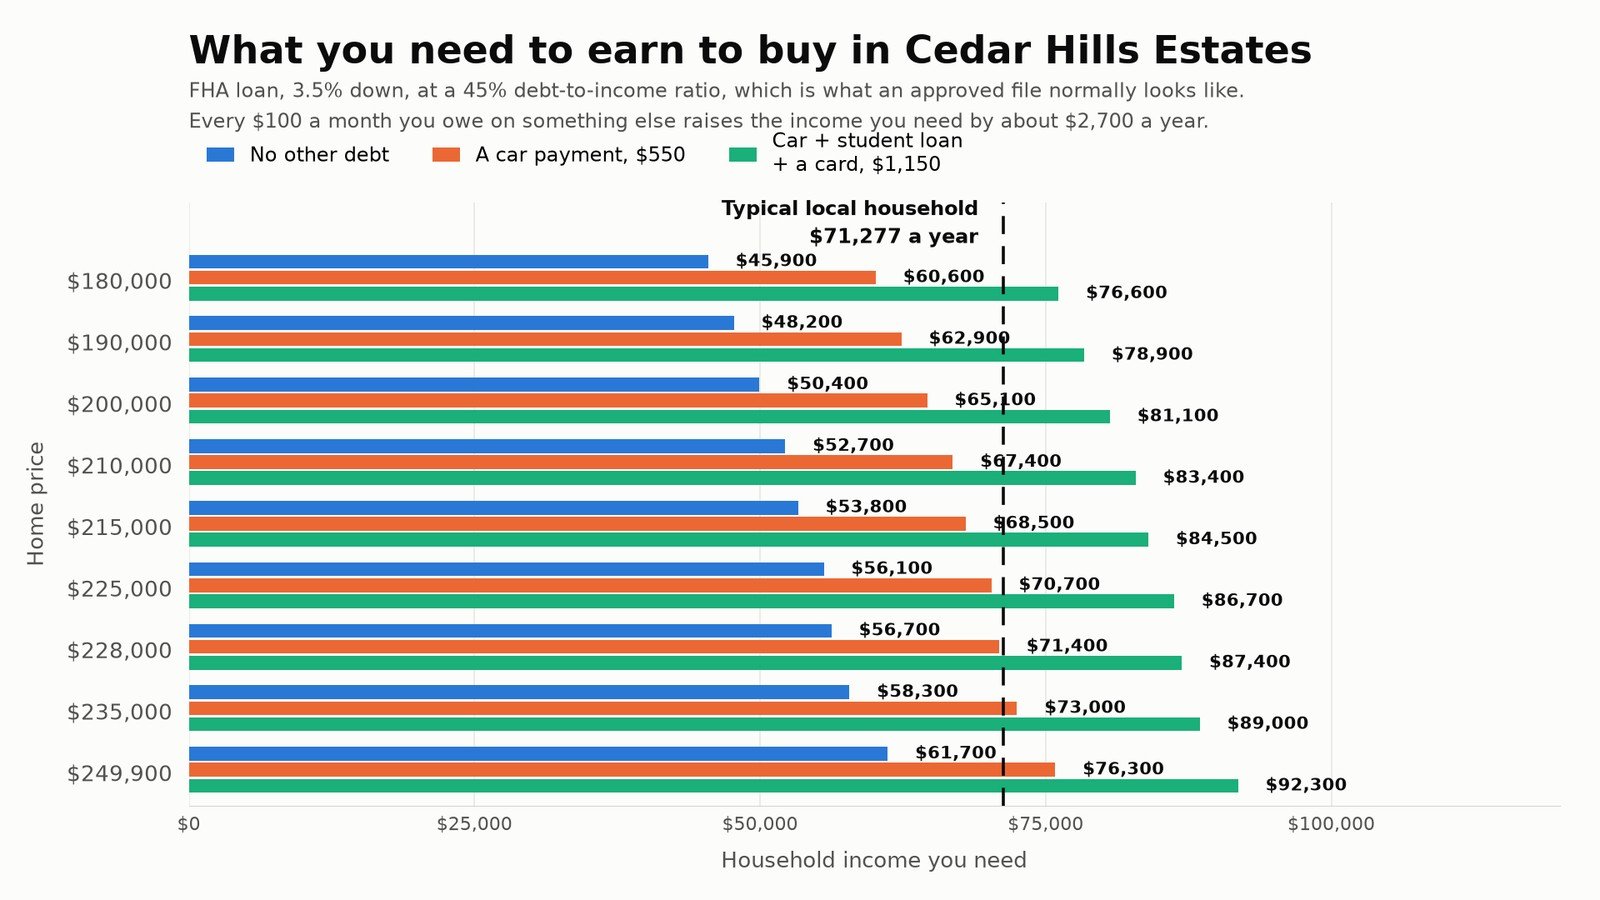
The entry home here needs about $45,900 a year to qualify. The most expensive one needs about $61,700. The typical Duval County household earns $71,277.
So every single home on the market in Cedar Hills Estates qualifies on a below-median income. That is unusual, and it did not hold in either of the first two neighborhoods in this series. San Jose Manor reached the median household. Lake Asbury could not be reached at all without equity from a previous sale. Here the whole range clears it, top to bottom. Add a $550 car payment and the entry figure moves to about $60,600, which still clears. Add a car, a student loan and a credit card at $1,150 a month and it is about $76,600, which finally does not.
What is actually for sale
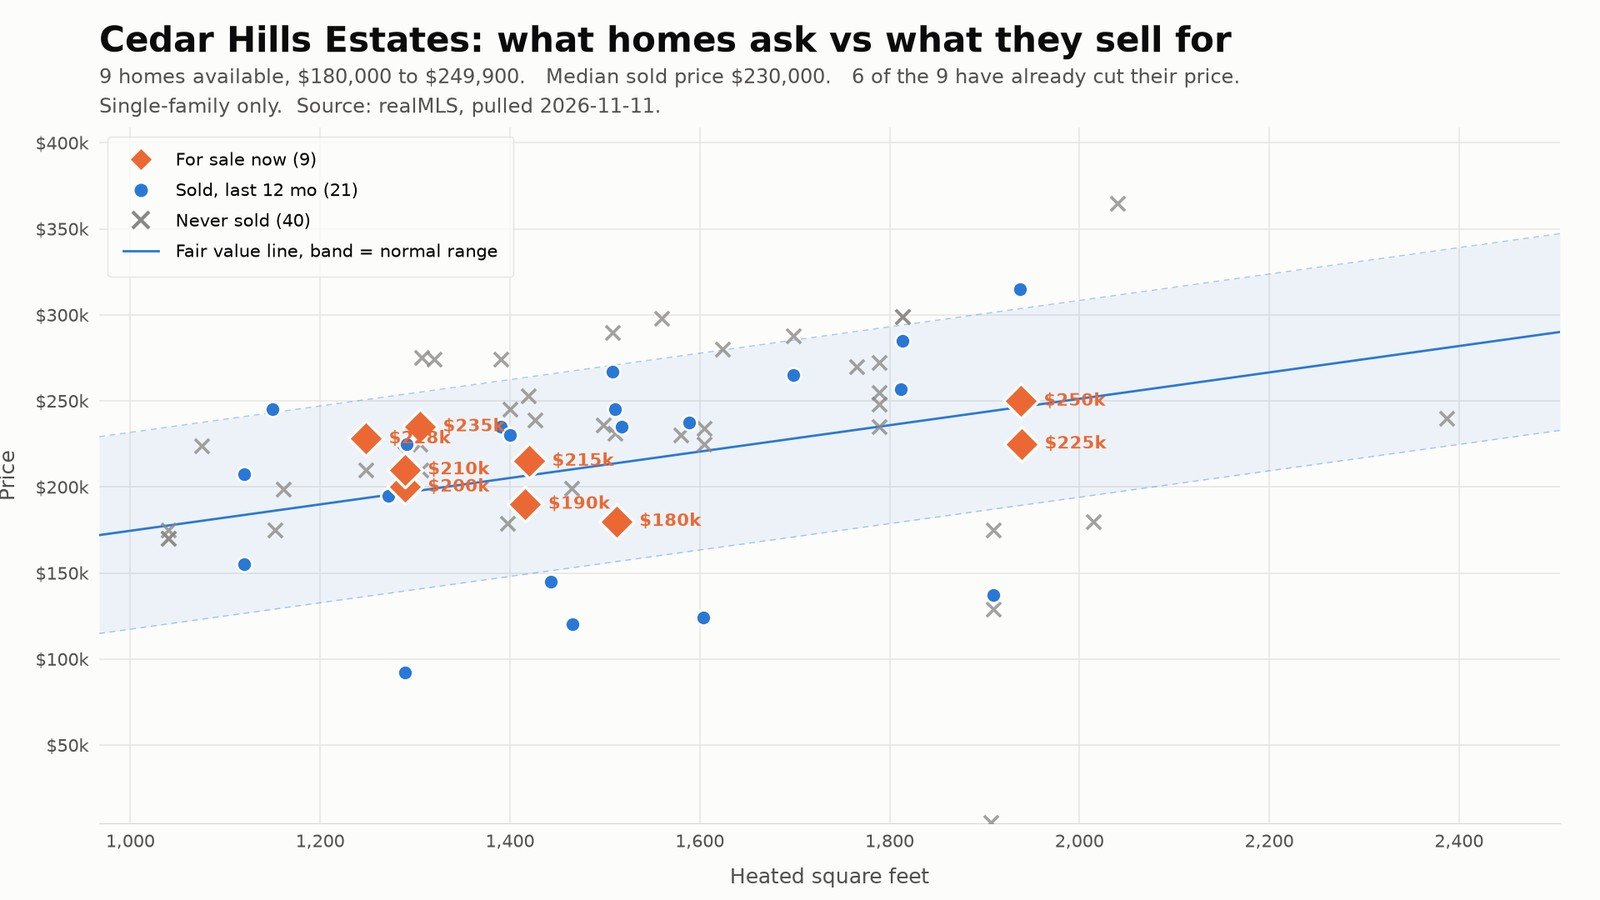
Nine single-family homes are available, from $180,000 to $249,900, with four more already under contract. The median home that closed in the last twelve months sold for $230,000, at about $156 a square foot. It is a 1950s neighborhood, with a median year built of 1958, and no CDD bond on a single one of the 100 records in this pull. Almost none of them carry an HOA.
The market here favours a buyer, and the data says so three different ways. Closings slowed by about a third, from roughly 2.2 a month in the prior six months to 1.5 a month in the last six. Six of the nine homes for sale have already cut their asking price, one of them by $64,999. And 42 of the 100 listing attempts in this pull died, cancelled, expired or withdrawn, without ever selling.
That last figure is the one worth sitting with. Nearly half of everything that tried to sell here failed. On the scattergram below, almost every one of those grey crosses sits above the fair value line, while the homes currently for sale sit on or below it. The ones still on the market have corrected. The ones that died never did. Priced right, homes here move.
What it costs a month
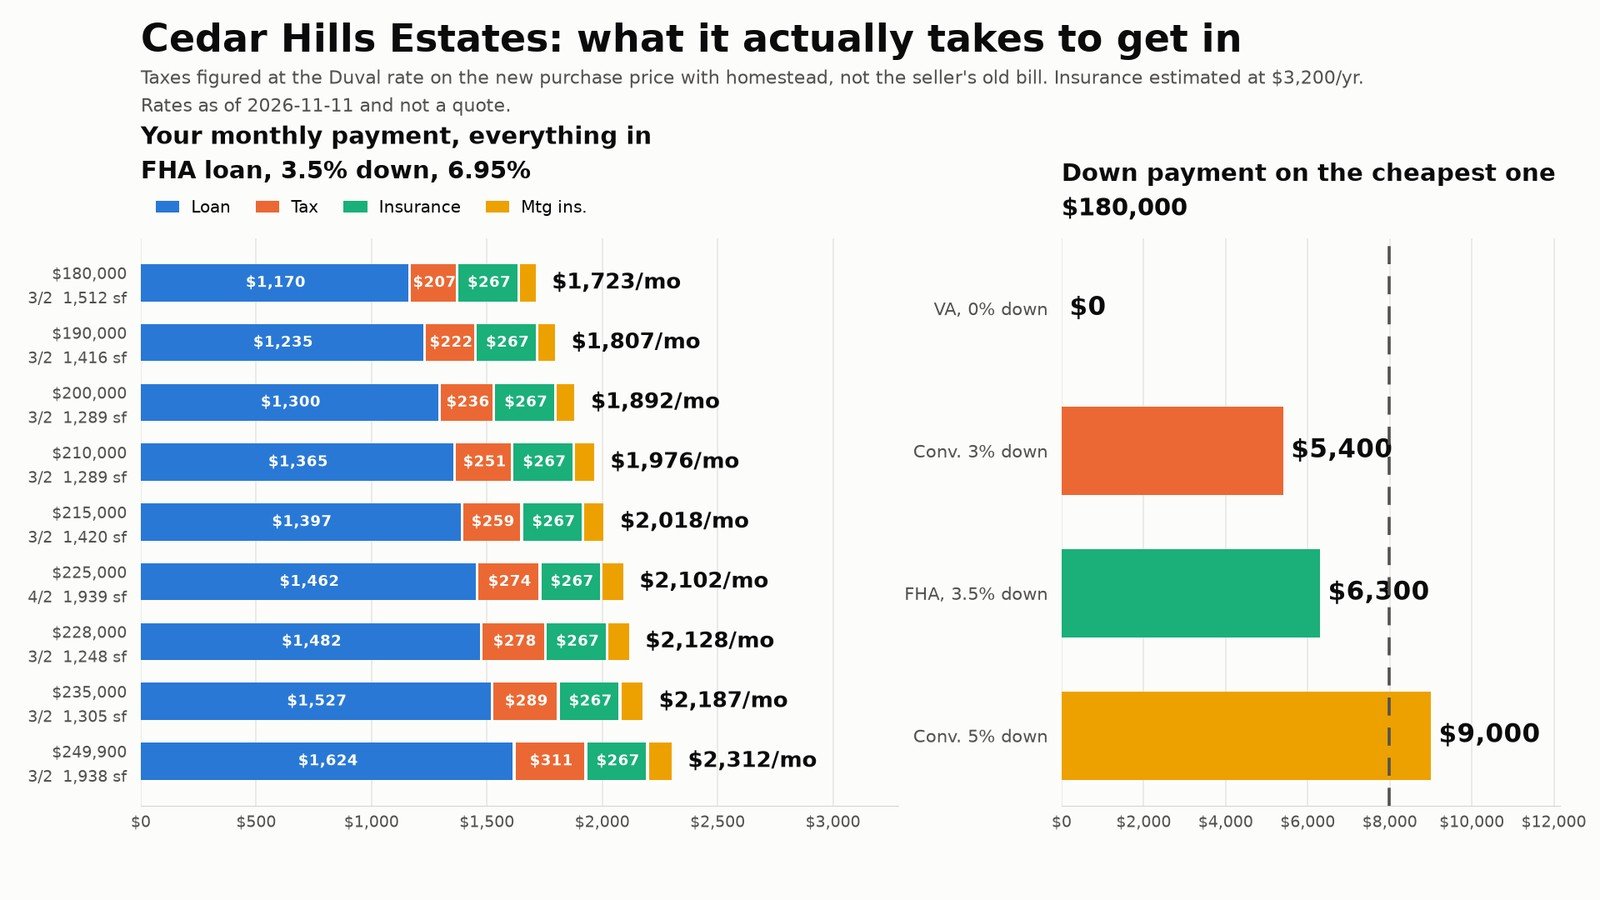
On an FHA loan at 3.5% down and 6.95%, with taxes and insurance included, payments run from $1,723 on the $180,000 home to $2,312 at $249,900.
Those taxes are modelled on the purchase price, not on the seller’s bill. Florida resets a property’s assessment to market value when it changes hands, so a long-held homesteaded owner’s tax figure on the MLS sheet can understate what a new buyer pays several times over.
What you need to close, and who pays it
The down payment itself is $6,300 to $8,746. But Florida closing costs and prepaid items add roughly another 2 to 5 percent of the price on top, so true cash to close lands around $10,000 to $21,000.
Here is what makes that manageable in this particular neighborhood. 13 of the 21 closings in the last twelve months carried a seller concession, at a median of $7,980 and a maximum of $12,000. That median credit is larger than the down payment on six of the nine homes currently for sale.
⚠️ A seller credit still cannot pay your down payment. It can only go toward closing costs, prepaid items, discount points and the upfront mortgage insurance premium, and the FHA minimum investment has to come from you or an approved gift. What it does is wipe out the other cash at the table, which is the larger and less expected number. The down payment is yours to bring. The seller is frequently covering nearly everything else.
The down payment does not have to come from your checking account either. A 401(k), stocks or a documented gift are all allowed sources.
⚠️ One per-listing check: two of the nine homes do not accept FHA financing by their listing terms. Nothing here is near the FHA loan ceiling, so this is a listing-by-listing issue rather than a price issue.
Credit score
580 is the real FHA floor at 3.5% down, and between 500 and 579 the program requires 10% down instead. Most lenders overlay above that and want 620 or better, so ask before you count yourself out. FHA is genuinely used here: 6 of the 21 closings in the last twelve months were FHA loans.
About the house in the video
The $200,000 home shown is 3748 Frye Avenue, and it is Bryce’s own listing. Three bedrooms, two baths, 1,289 square feet, built in 1958, on about a quarter acre. It carries a new mini split system, a recent roof and updated kitchen and baths. It was listed in September at $225,000 and has since been reduced to $200,000. At that price it takes about $7,000 down and $1,892 a month, and it accepts FHA financing.
Every figure on this page comes from one realMLS export pulled November 11, 2026, covering 100 single-family records in Cedar Hills Estates, Jacksonville 32210. These are generalities for a neighborhood, not an approval for a person. Every deal is its own puzzle.
- Every home on the market qualifies on a household income below the Duval County median of $71,277
- Nine homes for sale from $180,000 to $249,900, with a median sold price of $230,000
- Monthly payments of $1,723 to $2,312 on FHA at 3.5% down, taxes and insurance included
- Down payment of $6,300 to $8,746, and why true cash to close is closer to $10,000 to $21,000
- A median seller credit of $7,980 on 62% of closings, larger than the down payment on six of the nine homes
- Why 42 of 100 listing attempts died, six of nine have already cut, and closings slowed by a third
- No CDD on a single record, almost no HOA, and a 1958 median year built