Neighborhood Buyer Series

Lake Asbury, Florida: What a Move-Up Buyer Actually Needs

Published by Bryce Spraggins on

To move up into Lake Asbury in Green Cove Springs with $100,000 down, expect a monthly payment between $2,980 and $6,100 with taxes and insurance included, and a household income between roughly $79,600 and $162,800 with no other debt. Credit scores start around 620. Ten homes are for sale between $440,000 and $799,500, and the median home sold in the last twelve months at $620,000. Those figures are modelled on a conventional loan at 6.9% and the Clay County millage of 15.347, against a realMLS pull taken November 10, 2026.

Bryce Spraggins reads the real numbers on Lake Asbury in Green Cove Springs — what is for sale, what actually sold, and the payment, income and credit score it takes to move up with $100,000 of equity from your current home.

What This Video Covers

This is the Lake Asbury episode of the neighborhood buyer series. Every episode takes one neighborhood, pulls the real MLS data, and puts the four numbers a buyer actually needs on the screen: what is for sale, what it costs a month, what you have to earn, and what credit score gets you in.

Lake Asbury is in Green Cove Springs, southwest of Jacksonville in Clay County. It is about forty five minutes to the airport and forty to the stadium. This one is written for a move-up buyer rather than a first-time buyer, because the cheapest house in the neighborhood is $440,000 and the typical Clay County household earns $87,820. The math only opens up once you bring equity from the home you already own, so every figure here assumes $100,000 down from a previous sale.

What is actually for sale

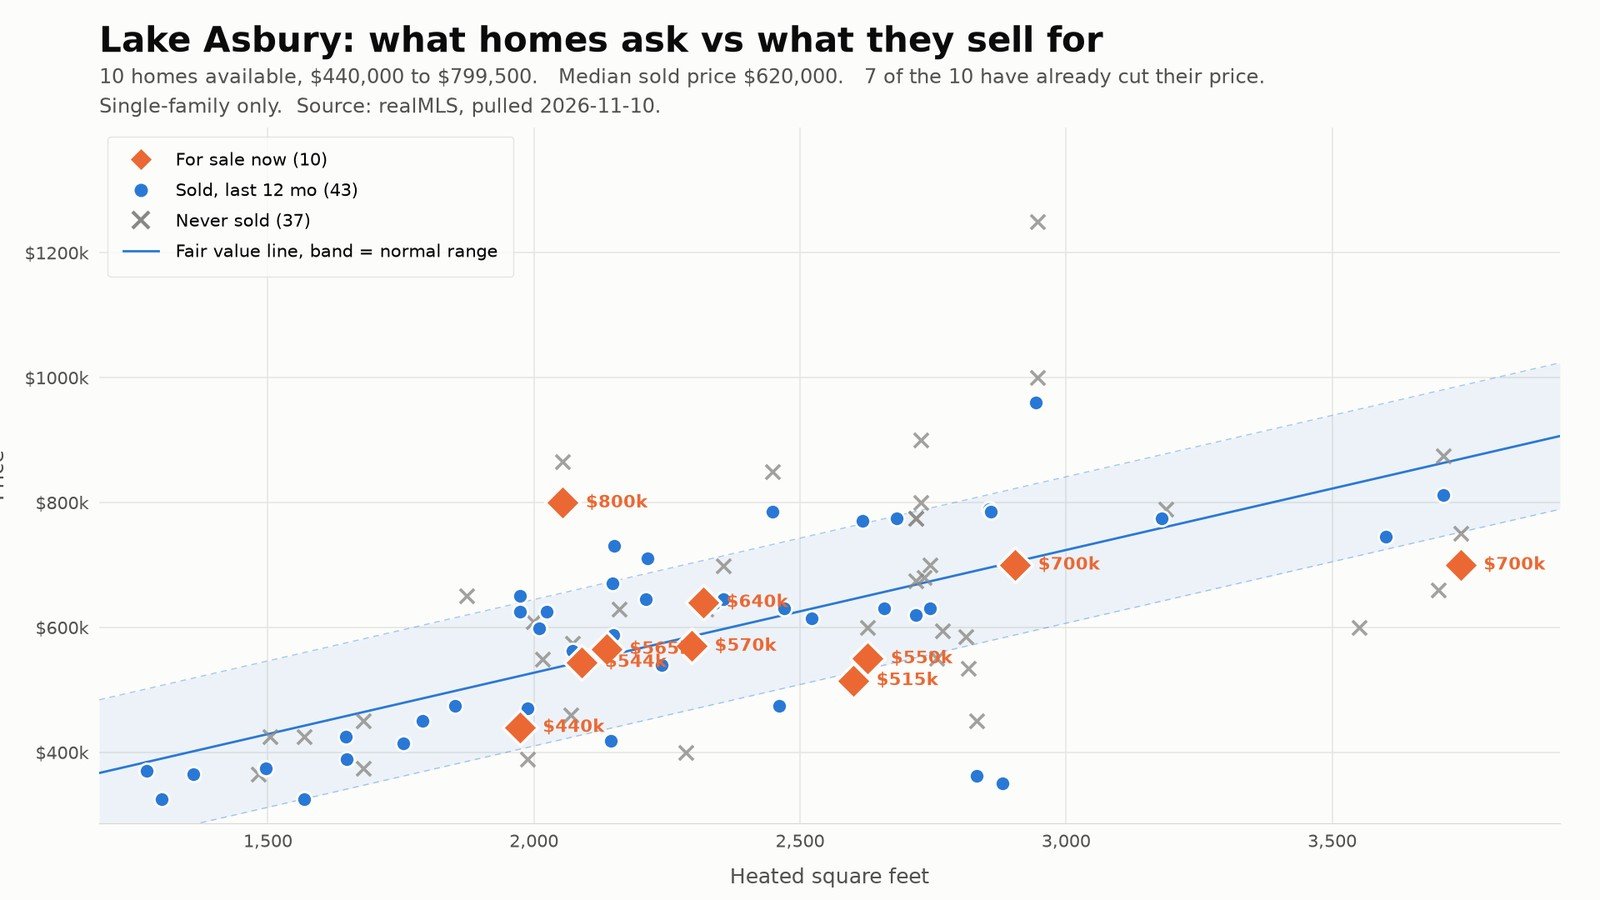
Ten single-family homes are available, from $440,000 to $799,500. The median home that closed in the last twelve months sold for $620,000, at about $257 a square foot. A lot of these sit on more than an acre, and some are on the water.

The thing worth knowing before you make an offer: asking prices here are negotiable and closing prices are the real ones. Seven of the ten homes currently listed have already cut their price, by as much as $75,001. Thirty-seven listings over the period gave up and never sold at all. And of the 43 homes that did close, 32 sold for less than they were asking — the median closed at 97.8% of ask. The market is not slow, it is just honest: closings actually sped up, from three a month in the prior six months to about four a month in the last six. Houses here sell, but they sell after a real reduction.

What it costs a month

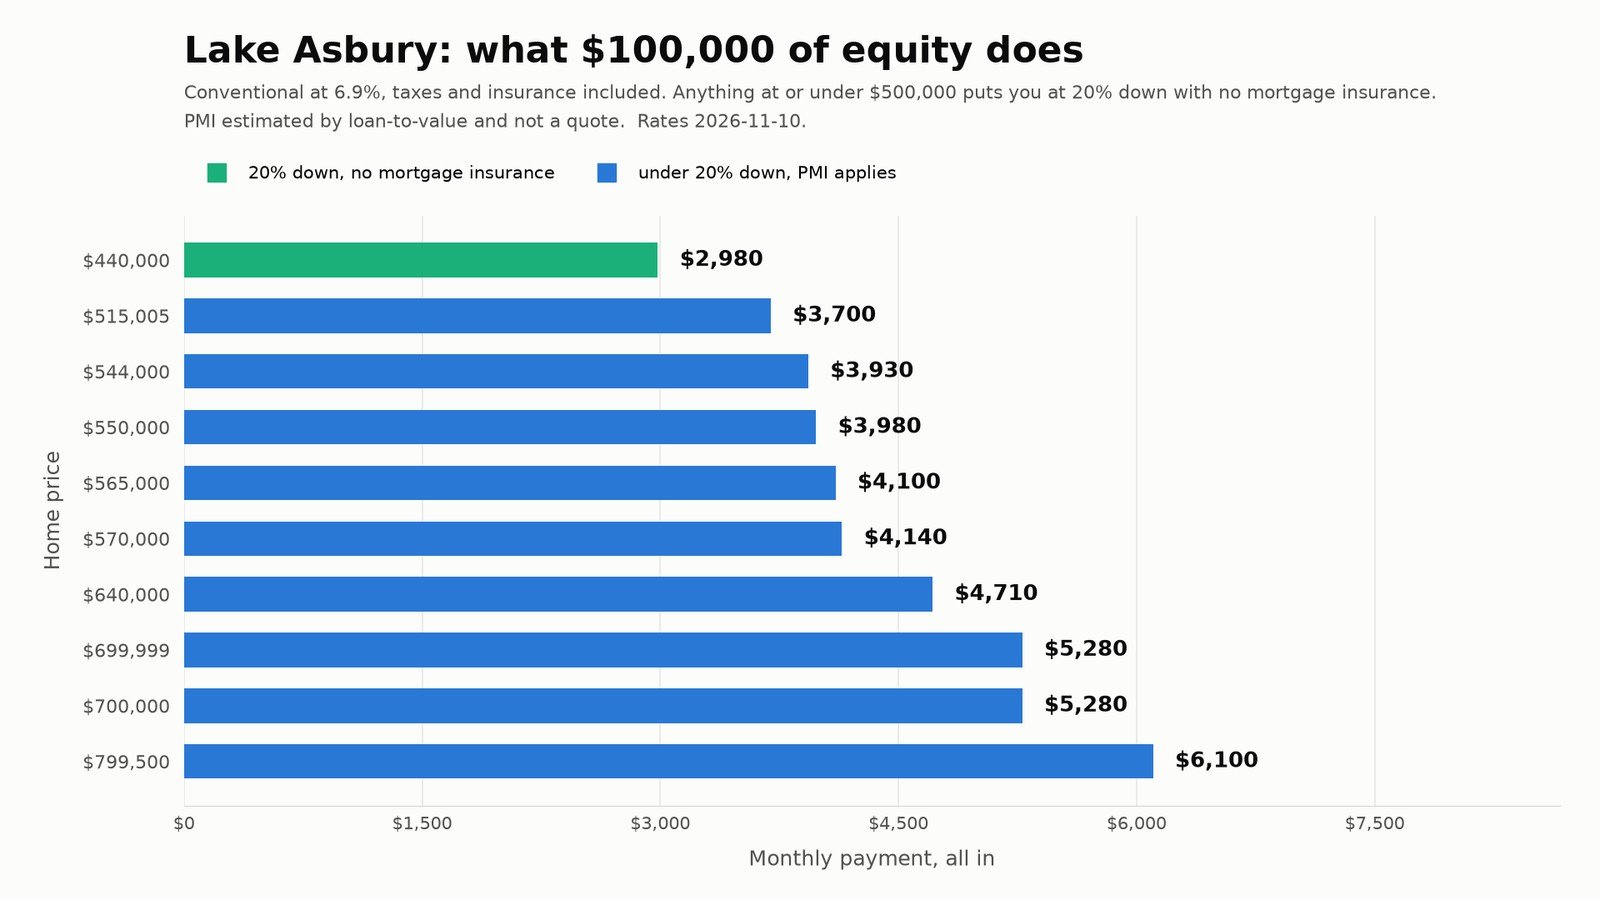
With $100,000 down on a conventional loan at 6.9%, taxes and insurance included, payments run from $2,980 on the entry home to $6,100 at the top of the market. At or under about $500,000 that $100,000 puts you at twenty percent down, which means no mortgage insurance at all.

Two carrying costs here are genuinely cheaper than Jacksonville. There was no CDD bond on a single one of the 111 records in this pull. Where an HOA exists it is nominal — $50 to $125 a year, and one of them is voluntary. And Clay County’s combined millage is 15.347 against Duval’s 17.86, so the tax rate is lower too.

One warning that applies to every Florida purchase: do not use the seller’s tax bill as your own. Florida resets the assessment to market when a house changes hands, so a long-held homesteaded seller’s bill can understate what you will pay by several times over. The payments above are modelled on the purchase price, not on what the current owner pays.

What you have to earn

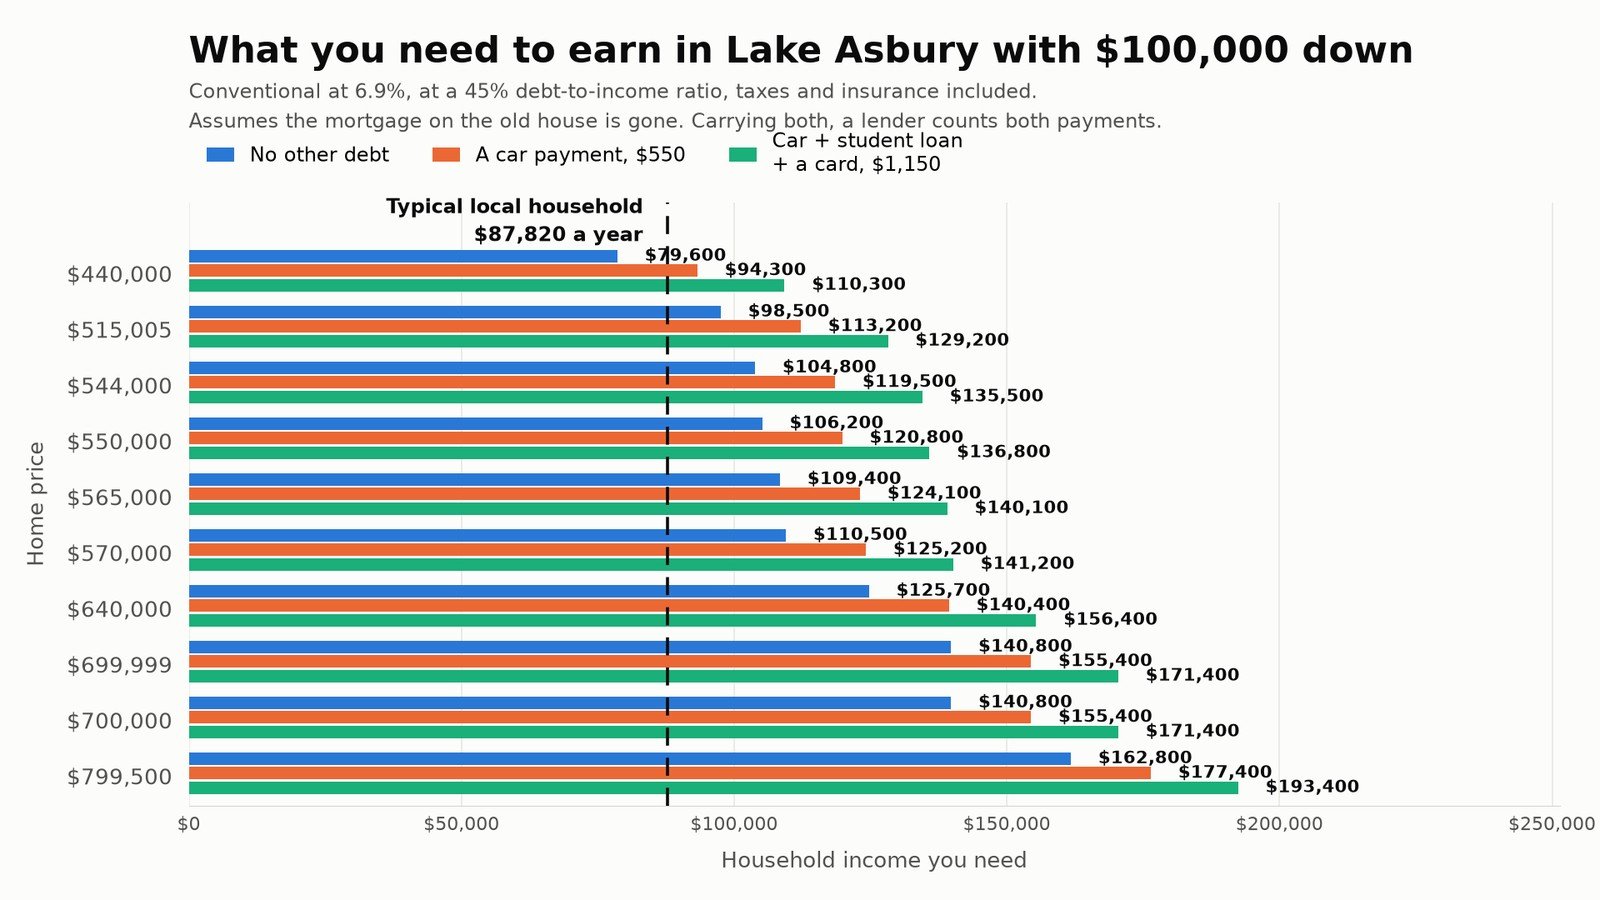
At a 45% debt-to-income ratio with no other monthly debt, the income needed runs from $79,600 on the $440,000 home to $162,800 at $799,500. Add a $550 car payment and the entry number moves to about $94,300. Add a car, a student loan and a card — call it $1,150 a month — and it is $110,300.

That is the approval number, not the comfortable number. A lender will approve a payment plenty of households would not want to actually live on, so run your own budget against the payment before you run it against the approval.

It also assumes the mortgage on your current home is gone. If you are carrying both, a lender counts both payments and these figures no longer apply.

Credit score

Scores start around 620 for a conventional loan. Lender overlays vary, and a stronger score buys a better rate rather than a yes or a no, so ask before you assume you are out.

About the house in the video

The home shown is 201 Dow Court, and it is Bryce’s own listing — worth saying out loud. It is a four bedroom, three bath home of about 2,627 square feet on 2.08 acres with 120 feet of water frontage, fully remodeled, with two full primary suites rather than one. It is listed at $550,000, reduced for a quick sale. For context on where that sits, the fair-value line in the scattergram below reads around $650,000 at that square footage, and the home plots underneath it.

Every number on this page comes from a single realMLS export pulled November 10, 2026, covering 111 single-family records in Lake Asbury, Green Cove Springs 32043 and Middleburg 32068. These are generalities for a neighborhood, not an approval for a person. Every file is its own puzzle.

The Actual Lake Asbury Numbers

Scattergram of Lake Asbury single-family homes plotting price against heated square feet, showing 10 homes for sale from $440,000 to $799,500, 43 sold in the last 12 months, 37 that never sold, and a fair value line with a normal range band
What homes ask versus what they sell for. Every single-family home in Lake Asbury plotted by heated square feet against price: the ten currently for sale, the 43 that closed in the last twelve months, and the 37 that never sold at all. The line is fair value and the band is the normal range around it. Note how many of the grey crosses sit above the band — those are the homes that asked too much and gave up. The $550,000 listing at 2,627 square feet plots below the line, which reads near $650,000 at that size. (Click to enlarge.)
Bar chart of monthly payments for ten Lake Asbury homes with $100,000 down, ranging from $2,980 at $440,000 to $6,100 at $799,500, with the $440,000 home marked as having no mortgage insurance
What $100,000 of equity does to the payment. Every available home, conventional at 6.9%, taxes and insurance included. The green bar is the one where $100,000 lands you at twenty percent down, so no mortgage insurance applies at all. Everything above about $500,000 carries PMI until the loan-to-value comes down. PMI here is estimated from loan-to-value, not quoted. (Click to enlarge.)
Grouped bar chart of household income needed to buy in Lake Asbury with $100,000 down under three debt scenarios, from $79,600 to $193,400, against a typical local household income of $87,820
The household income each price actually requires. Three debt loads per home at a 45% debt-to-income ratio: no other debt, one $550 car payment, and a car plus a student loan plus a credit card at $1,150 a month. The dashed line is the typical Clay County household at $87,820 a year — which reaches the entry home only once $100,000 of equity is in play. It assumes the mortgage on the old house is gone; carrying both, a lender counts both payments. (Click to enlarge.)

Common Questions

What income do you need to buy a house in Lake Asbury, Florida?

With $100,000 down and no other monthly debt, a household needs roughly $79,600 a year for the entry home at $440,000, and about $162,800 for the top of the market at $799,500. A $550 car payment raises the entry figure to about $94,300, and a car plus a student loan plus a credit card raises it to about $110,300. Those are modelled on a conventional loan at 6.9% at a 45% debt-to-income ratio, with taxes and insurance included, and they assume the mortgage on your current home has been paid off at closing.

How much are homes in Lake Asbury?

As of November 10, 2026, ten single-family homes were for sale in Lake Asbury between $440,000 and $799,500. The median home that closed in the previous twelve months sold for $620,000, at about $257 a square foot. Seven of the ten homes then listed had already reduced their asking price, and 32 of the 43 homes that closed sold for less than they were asking.

What credit score do you need to buy in Lake Asbury?

Around 620 for a conventional loan. Individual lenders set their own overlays above the program minimum, and above that threshold a higher score generally buys a better interest rate rather than deciding approval outright. Ask a lender about your specific file before assuming a score rules you out.

Does Lake Asbury have a CDD or high HOA fees?

No. Across all 111 single-family records in the November 2026 MLS pull, not one carried a CDD bond. Thirty-six of them carried an HOA fee, and those ran $50 to $125 per year, with one listed as voluntary. Clay County's combined millage is 15.347 compared with Duval County's 17.86, so the property tax rate is lower than Jacksonville as well.

Why is the seller's property tax bill not what I will pay?

Florida reassesses a property to market value when it changes hands. An owner who has held a homesteaded property for years has a capped assessment well below what the house is worth, so their current tax bill can understate a new buyer's bill several times over. Always model the tax from the purchase price and the county millage, never from the figure on the MLS sheet.

Do sellers in Lake Asbury help with closing costs?

Frequently. Of the 43 homes that closed in Lake Asbury in the twelve months to November 2026, 23 carried a seller concession, with a median of $9,000 and a maximum of $18,984. A seller credit can only be applied to closing costs, prepaid items, discount points and mortgage insurance premiums. It cannot be used for your down payment, which has to come from you or an approved gift.

Related Resources

Want These Numbers for Your Neighborhood?

Tell Bryce where you want to be and he will run the same read on it — what is for sale, the payment, the income and the credit score it takes to get in. No obligation, and no property address required.