What This Video Covers
This is the first episode of the neighborhood buyer series. Each one takes a single neighborhood, pulls the real MLS data, and puts the four numbers a first-time buyer actually needs on the screen: what is for sale, what it costs a month, what you have to earn, and what credit score gets you in.
San Jose Manor sits in the 32217 zip code, minutes from San Marco, the stadium and NAS Jax. The argument for buying here is not that it is your dream home. It is that the first home is the milestone that gets you to the second one: nobody can make you move, and you start building the equity that pays for the next house.
What is actually for sale
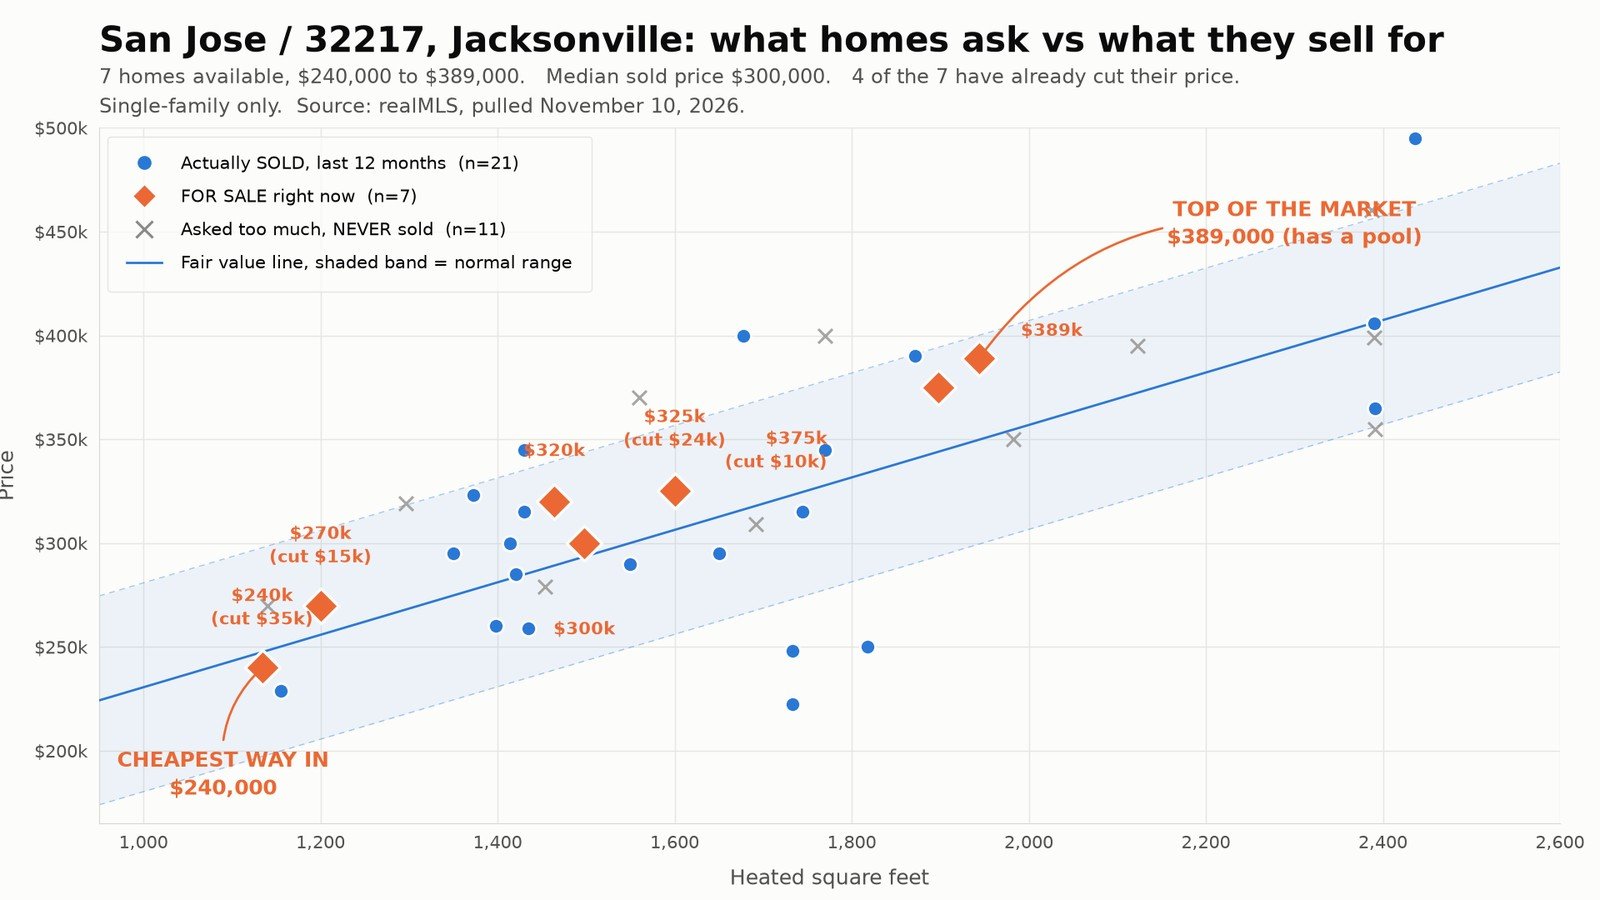
Seven single-family homes are available, from $240,000 to $389,000. The median home that closed in the last twelve months sold for $300,000, at about $195 a square foot.
This neighborhood is one where a buyer currently has room to negotiate, and the data says so three different ways. Closings slowed by about a third, from roughly 2.2 a month in the prior six months to 1.5 a month in the last six. Four of the seven homes on the market have already cut their asking price, one of them by $35,000. And eleven listings over the period gave up and never sold at all. When that many sellers are waiting, the buyer who is ready to move has leverage.
What it costs a month
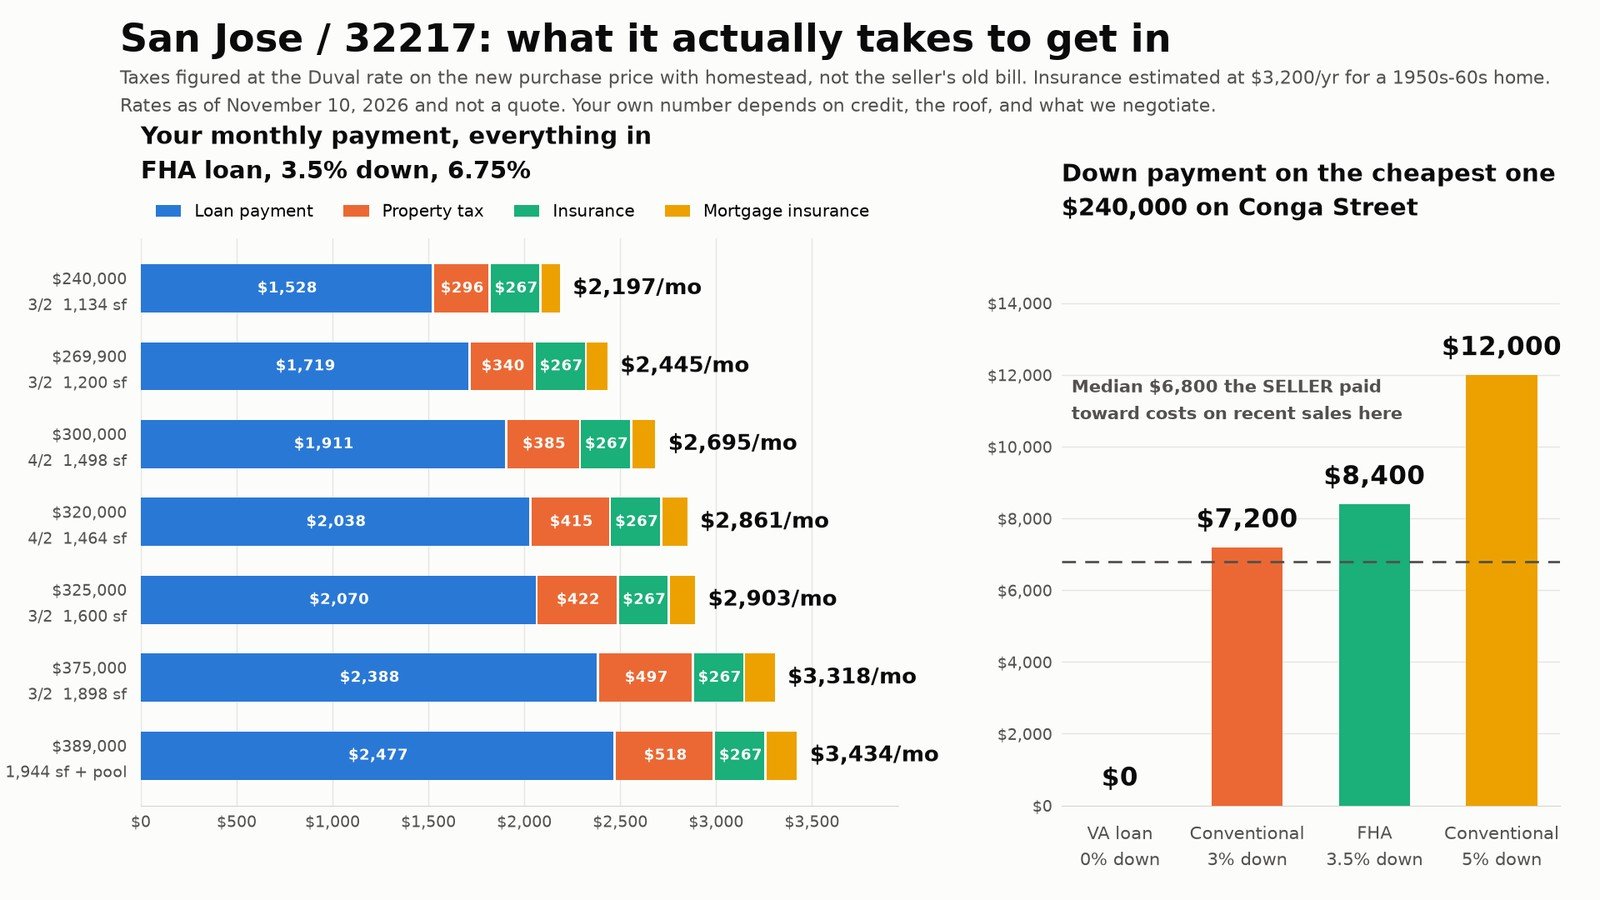
On an FHA loan at 3.5% down and 6.75%, with taxes and insurance included, payments run from $2,197 on the $240,000 home to $3,434 at $389,000. A $300,000 home sits at about $2,695.
Those taxes are modelled on the purchase price, not on the seller’s bill. Florida resets a property’s assessment to market value when it changes hands, so a long-held homesteaded owner’s tax figure on the MLS sheet can understate what a new buyer pays several times over. It is the single most common unpleasant surprise two hours after a showing.
The down payment, and who actually pays it
FHA at 3.5% down runs $8,400 on the $240,000 home and $13,615 at $389,000. A VA loan is zero down. Conventional runs 3% or 5%.
Here is the part worth understanding properly. Sellers in this neighborhood are contributing real money: 14 of the 22 closings in the last twelve months carried a seller concession, at a median of $7,000 and a maximum of $17,375. The most recent was 4040 Sierra Madre Drive, which closed on November 3 with the seller paying $12,600.
⚠️ A seller credit cannot pay your down payment. It can only go toward closing costs, prepaid items, discount points and the upfront mortgage insurance premium. The FHA minimum investment has to come from you or an approved gift. What the credit does is wipe out the other cash you would have needed at the table, which in Florida runs another two to five percent of the price on top of the down payment. That is a large difference, and it is the reason "what you need to close" is a bigger number than the down payment alone.
And the down payment itself does not have to come out of your checking account. A 401(k), stocks, or a documented gift are all allowed sources.
⚠️ One more per-listing check: not every home accepts FHA financing. Two of the seven on the market here take cash, VA or conventional only, including the $300,000 home shown in the video. The FHA figures above are the program’s math, not a guarantee that a given house will take that offer, so tie the number to a specific price and check the listing terms before you plan around it.
What you have to earn
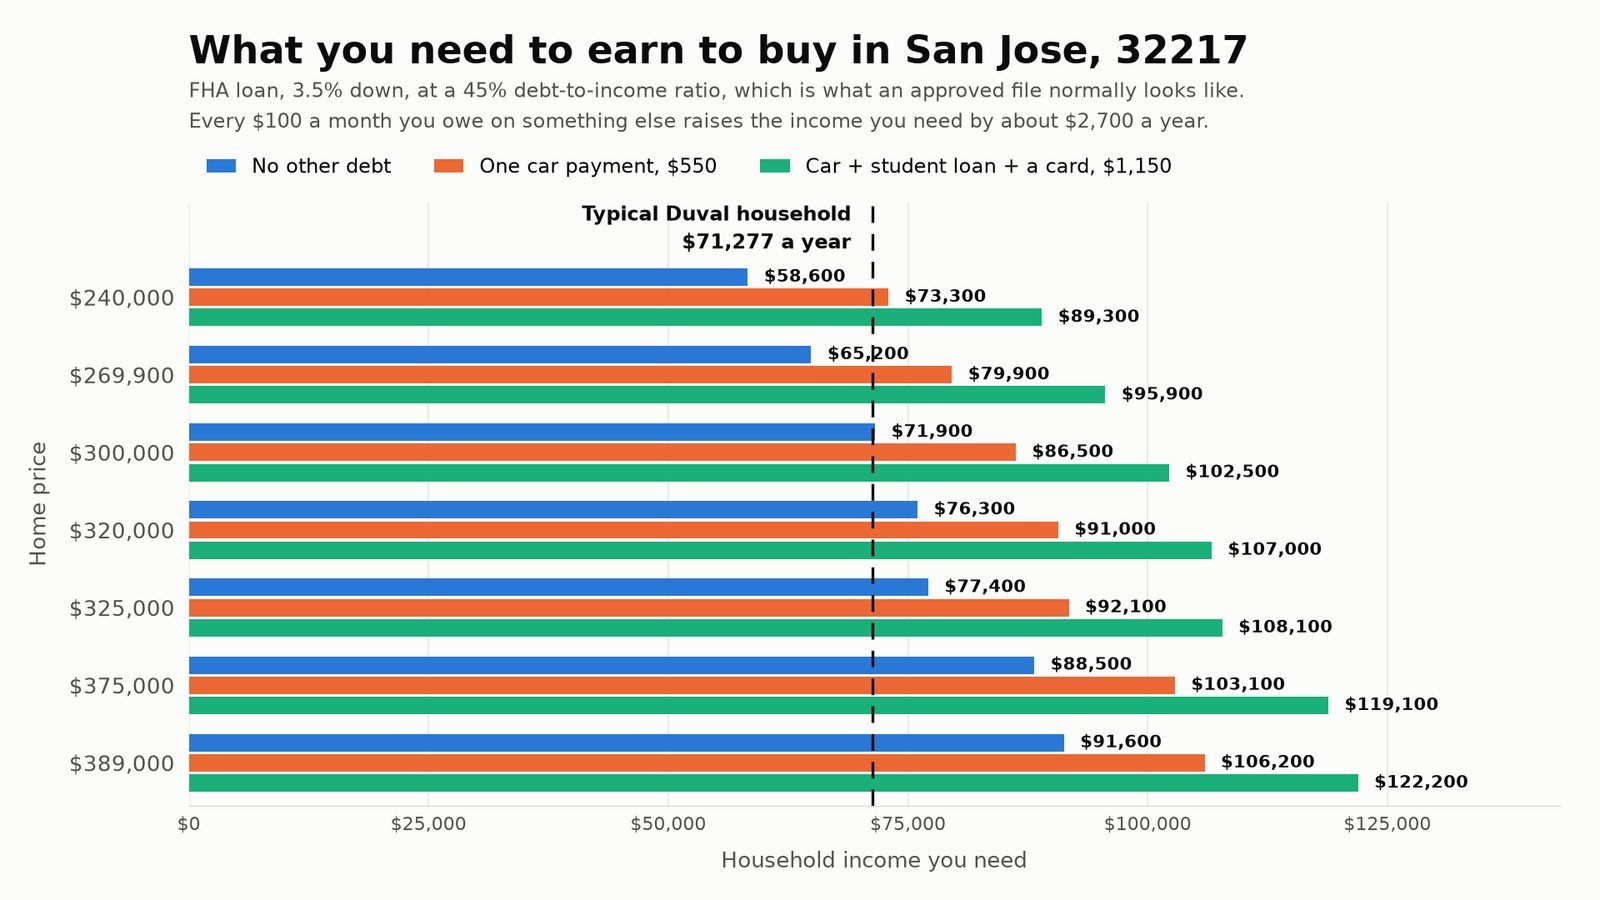
At a 45% debt-to-income ratio with no other monthly debt, the income needed runs from $58,600 at $240,000 to $91,600 at $389,000. Add a $550 car payment and the entry figure moves to about $73,300. Add a car, a student loan and a credit card at $1,150 a month and it is about $89,300. The typical Duval County household earns $71,277, which reaches well past the entry home.
That income figure is what a lender will approve, not what is comfortable to live on. Run the payment against your own budget before you run it against an approval.
Credit score
580 is the real FHA floor at 3.5% down, and between 500 and 579 the program requires 10% down instead. Most lenders overlay on top of that and want 620 or better, so ask rather than assume you are out. A bigger down payment also brings the payment itself down, which is a separate lever from the score.
About the house in the video
The $300,000 home shown is 7913 Napo Drive, and it is Bryce’s own listing. Recently renovated with new floors and paint throughout, updated bathrooms, stainless kitchen appliances and an oversized lot. As noted above, its listing terms do not include FHA.
Every figure on this page comes from one realMLS export pulled November 10, 2026, covering 62 single-family records in San Jose Manor, Jacksonville 32217. These are generalities for a neighborhood, not an approval for a person. Every deal is its own puzzle.
- Seven homes for sale from $240,000 to $389,000, with a median sold price of $300,000
- Monthly payments of $2,197 to $3,434 on FHA at 3.5% down, taxes and insurance included
- Down payments of $8,400 to $13,615, and the VA and conventional alternatives beside them
- Why 14 of 22 recent closings carried a seller credit, median $7,000 — and why that credit legally cannot pay your down payment
- Household income of $58,600 to $91,600 with no other debt, against a typical Duval household of $71,277
- Why closings slowed by a third, 4 of 7 listings have already cut, and 11 gave up entirely
- The 580 FHA floor, the lender overlays above it, and why a bigger down payment lowers the payment too