A homeowner who owes more than the property will sell for has three realistic options, and only one of them pays anything. This 2022-built Jacksonville townhome carried an estimated mortgage payoff near $152,500 in a community where nothing had closed in nine months and the home itself had already failed to sell after 369 days on the market. An as-is cash offer of $100,000 leaves roughly $52,500 still owed to the lender, so it cannot be accepted at all. Listing it at $175,000 nets about $938 after commissions, closing costs and the payoff — it ends the mortgage but pays nothing. Owner financing at $225,000 with 15 percent down, 4.5 percent interest amortized over 40 years and a balloon in year ten pays roughly $13,373 at the closing table, about $110 a month for ten years, and about $61,334 when the balloon is paid — close to $88,000 in total.

Real Offers · Arlington, Jacksonville

He Owes More Than It Will Sell For — Three Real Offers

By Bryce Spraggins · September 15, 2026

1,110 sq ft townhome · built 2022 · priced off twelve months of activity inside the same community

A real offer on a Jacksonville townhome worth less than its mortgage. The $100,000 cash number and why it cannot close, what listing it actually nets, and an owner-financing structure that pays about $88,000 over ten years.

The address and the homeowner's name are never shown. Everything else — the condition, the comps, and the number — is exactly what happened.

The Offer

September 15, 2026

The frozen comp set, the estimated payoff, the $100,000 cash number that cannot close, what listing actually nets, and the owner-financing structure that pays about $88,000 over ten years.

How This Number Was Built

Most offer videos compare two numbers. This one has to compare three, because the first two do not work. The owner bought a brand-new townhome in 2022 and owes more on it today than the community will pay for it — which changes what an offer even means. The question stops being how much and becomes can this close at all.

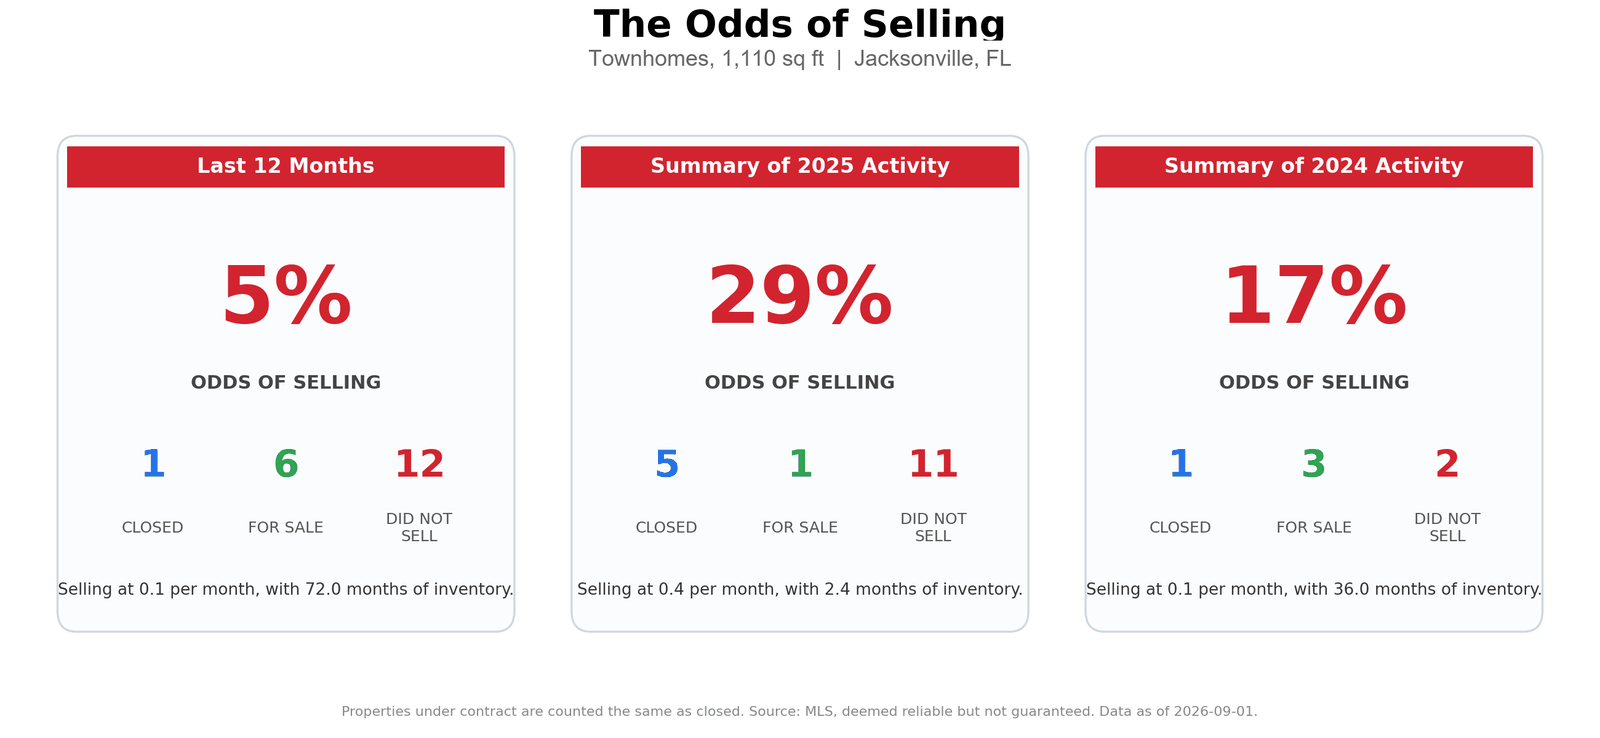
The market repriced and then stopped. Pulling every sale and every attempted sale in the community for twelve months returns a single closed transaction, six homes currently for sale, and twelve that were listed and never sold. That is a 5 percent chance of selling and roughly 72 months of inventory. Six units did close between $200,000 and $235,000, but the most recent of those was December 2025 and nothing has closed since. Three homes are asking between $189,000 and $195,000 right now and none of them are moving. This particular home is the clearest evidence of all: it was listed for 369 days at $199,990 and came off the market unsold two weeks before this video was made. A price nothing clears at is not the market price, which is why the working numbers here are $175,000 on a good day and $150,000 as a floor rather than anything the older closings suggest.

The payoff is the whole problem. Working from the original 2022 loan amount at the interest rates of that spring, and assuming every payment was made on time, the balance today lands near $152,500. That single figure decides all three options.

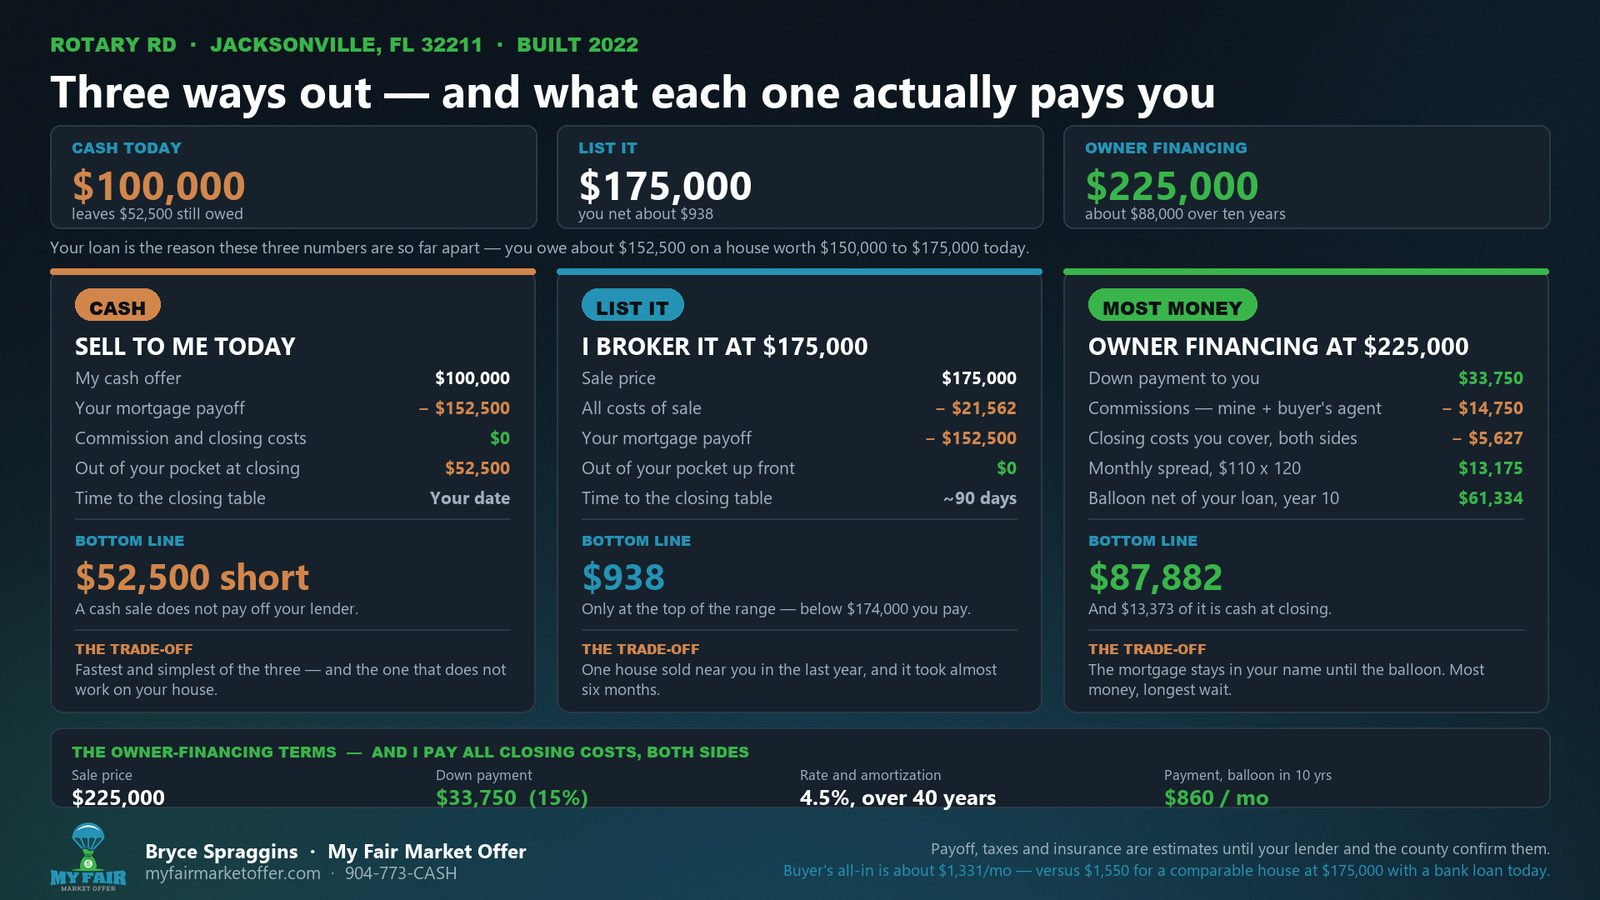
Door one, cash. Starting from a $150,000 safe-side resale, taking out the profit margin a cash home buyer has to hold and the cost of making it market-ready leaves a cash offer of $100,000. Against a $152,500 payoff that leaves roughly $52,500 still owed, which the seller would have to bring to the closing table. It is the fastest and simplest option and it is the one that cannot be used.

Door two, listing it. At $175,000, after a $8,000 listing fee, a buyer-side commission, a budget for the buyer’s closing costs and the seller’s own, the net lands near $938 — and only at the very top of the range. Below about $174,000 the seller starts bringing money to closing instead of leaving with it. Listing ends the mortgage; it does not pay for the move.

Door three, owner financing. Selling a payment instead of a price lets the number move up. At $225,000 with 15 percent down, 4.5 percent amortized over 40 years and a balloon in year ten, the buyer pays about $860 a month — roughly what a new loan on a $150,000 home costs at today’s rates, which is what makes it sellable. The seller pays every closing cost on both sides, which is a far cheaper promise than it sounds because owner financing has no lender and therefore no origination, appraisal or underwriting. After both commissions and those costs he walks from the table with about $13,373, collects roughly $110 a month for ten years, and is paid about $61,334 when the balloon comes due. Roughly $88,000, against $938 for listing it.

The catch, said out loud. The mortgage stays in his name until the balloon is paid, so if the buyer stops paying he still owes it. A third-party loan servicer handles the escrow, pays the underlying mortgage and makes a missed payment visible immediately, which protects both sides. And the balloon — about $169,689 against a home in this price range — is low enough that the buyer can refinance without the property appreciating at all. That is the reason the down payment is 15 percent and not 10.

The Actual Comps

These are the real charts this offer was priced from — not a re-creation.

Offer summary comparing a $100,000 cash offer that leaves $52,500 still owed, a $175,000 listing netting $938, and owner financing at $225,000 paying about $88,000 over ten years
The summary from the end of the video: all three doors side by side, each carried down to what the seller actually keeps. Cash pays the most quickly and cannot be used at all — $100,000 against a $152,500 payoff leaves $52,500 still owed. Listing at $175,000 nets about $938, and only at the very top of the range; below roughly $174,000 the seller brings money to the table instead. Owner financing at $225,000 pays about $88,000, but in three pieces across ten years rather than one check. The band across the bottom carries the full owner-financing terms, because a seller is going to ask for them. (Click to enlarge.)
Odds of selling chart showing 5 percent odds over the last twelve months with one closed sale, six for sale and twelve that did not sell, against 29 percent in 2025 and 17 percent in 2024
The chart the whole offer rests on. Over the last twelve months this community produced one closed sale, six homes still for sale, and twelve that were listed and never sold — a 5 percent chance of selling and about 72 months of inventory. The middle panel shows what changed: calendar 2025 had five closings and 2.4 months of inventory, so this is not a community that was always frozen. It repriced and then stopped. Six homes did close between $200,000 and $235,000, but the most recent was December 2025 and nothing has closed since — which is why the working numbers in this offer are $175,000 and $150,000 rather than anything those older sales suggest. (Click to enlarge.)

Common Questions

Can you sell a house if you owe more than it is worth?

Yes, but not with a conventional sale, because the mortgage has to be paid in full at closing. If the sale price minus commissions and closing costs comes to less than the payoff, the seller has to bring the difference in cash or the deal cannot close. On this townhome the payoff was about $152,500 and a $100,000 cash offer would have left roughly $52,500 still owed. The realistic routes are listing at the very top of the range so the net just covers the payoff, negotiating a short sale with the lender, or owner financing, which raises the price by selling a payment rather than a price.

How does owner financing pay a seller more than a cash offer?

Because the buyer is no longer shopping on price, they are shopping on the monthly payment and the down payment. A buyer who cannot qualify for a bank loan will pay a higher price for terms they can actually get, so the seller can ask above what a cash sale or even a listing would bring. The trade is time. Instead of one check at closing the seller receives a down payment, a monthly spread over their existing mortgage payment, and a balloon payment years later. On this townhome that structure came to roughly $88,000 over ten years against about $938 from listing it.

What is a balloon payment in owner financing?

It is the entire remaining balance, due in full on a set date. The monthly payment is calculated on a long amortization schedule so it stays affordable, but the loan is not scheduled to run that full term. On this townhome the payment was amortized over 40 years while the balloon came due in year ten, which keeps the payment near $860 a month and still pays the seller off in a decade. The buyer has to refinance or sell to satisfy it, so the balloon amount matters: here it lands near $169,689, low enough to refinance without the property gaining any value.

Why would a cash home buyer offer so much less than the home sold for new?

Because the offer is built off what the property will sell for now, not what it sold for then. This townhome was built in 2022, but the community has one closed sale in the last twelve months, twelve homes that were listed and never sold, and roughly 72 months of inventory. Three units are asking between $189,000 and $195,000 with no takers, and this home itself sat 369 days at $199,990 without selling. The cash offer starts from a conservative resale figure and subtracts the profit margin and the cost of making it market-ready.

Why use a third-party loan servicer on an owner-financed sale?

Because it protects both sides of a deal where the original mortgage is still in the seller's name. The servicer collects the buyer's payment, pays the underlying mortgage from it, and holds the escrow for taxes and insurance. The seller gets immediate notice if a payment is missed rather than finding out when their own lender calls, and the buyer gets proof that the money is reaching the loan and the escrow. It removes the single largest objection to buying a home on owner-financed terms.

Related Resources

Want Your Own As-Is Cash Offer?

Tell us about the house and you'll get a real as-is cash offer to purchase your home — no repairs, no showings, no commissions. Same process, same honesty, and you'll hear the number out loud.